
Dual Pricing vs Cash Discount vs Surcharging: How to Stay Compliant
CEO – Nationwide Payment Systems
Dual pricing, cash discounting and surcharging are three legitimate ways to stop absorbing the full cost of card processing, and the one you choose matters less than whether you set it up the right way. Dual pricing shows a card price and a lower cash price side by side, a cash discount posts the card price and takes money off when a customer pays another way, and a surcharge adds a disclosed fee to credit card sales only. Our recommendation, after setting these programs up for merchants since 2001, is dual pricing for most stores, restaurants and service counters, surcharging mainly for invoices and payment links, and plain traditional pricing for the business that would rather not touch its prices at all. This guide explains how each model works, what the card networks and state laws expect, the compliance checklist we use, the mistakes that get merchants fined, and how to decide which one fits you.
The short answer
- If you sell in person, at a counter or a table: dual pricing is usually the clearest choice, because the customer sees both prices before paying and nothing is added at the end.
- If you post one price and want cash payers rewarded: a cash discount program works, as long as the posted price is the card price and the discount shows up on the receipt.
- If you bill other businesses by invoice or payment link: a properly registered surcharge on credit cards can make sense, and it is often easier for those customers to follow than it is at a busy register.
- If your customers are very price sensitive or your system cannot show matching prices everywhere: keep traditional pricing until it can, because a sloppy program costs more than the fees it was meant to cover.
- Whatever you choose, confirm the current card network rules with your processor and, for any legal question, with an attorney, because the rules and state laws change.
Three ways to handle the cost of accepting cards
Every time a customer taps, dips, swipes or types in a card number, your business pays to accept that payment. Part of the cost is interchange, which goes to the bank that issued the customer’s card. Part of it is the assessment charged by the card network itself. The rest is what your payment processor charges for moving the money. Most business owners never see those pieces separately, they just see the total come out of every sale, and for a store or restaurant on thin margins that total has become one of the largest bills it pays.
There are three common ways to recover that cost, and they are not interchangeable. They are described differently, regulated differently and shown to the customer differently, which is exactly why so many merchants get into trouble by calling one of them by the other’s name.
Dual pricing
Dual pricing means showing two prices for the same item: a card price and a cash price. The customer sees both before paying and chooses how to pay. Because both prices are posted up front, nothing is added at the end of the sale and nobody is surprised at the register. Gas stations have priced this way for decades, which is why most customers already understand it the moment they see it.
Cash discount
A cash discount program posts the card price as the standard price on your shelves, menus and invoices, then takes a discount off when the customer pays with cash or another lower-cost method. It is structured as a discount for paying a different way, not as a penalty for using a card, and that distinction is the whole reason it is treated differently from a surcharge. When it is set up correctly, the customer pays the posted price by card and pays less by cash, and the receipt shows the discount.
Surcharging
A surcharge adds a fee on top of the price, and only when the customer pays with a credit card. It can never be applied to debit cards, it must be disclosed before the customer pays, it must appear as its own line on the receipt, and card network rules limit how much it can be. Surcharging tends to work best where the customer reads the bill before paying, such as a B2B invoice or an online payment link, because explaining a surcharge to a line of shoppers at a register is harder than it sounds.
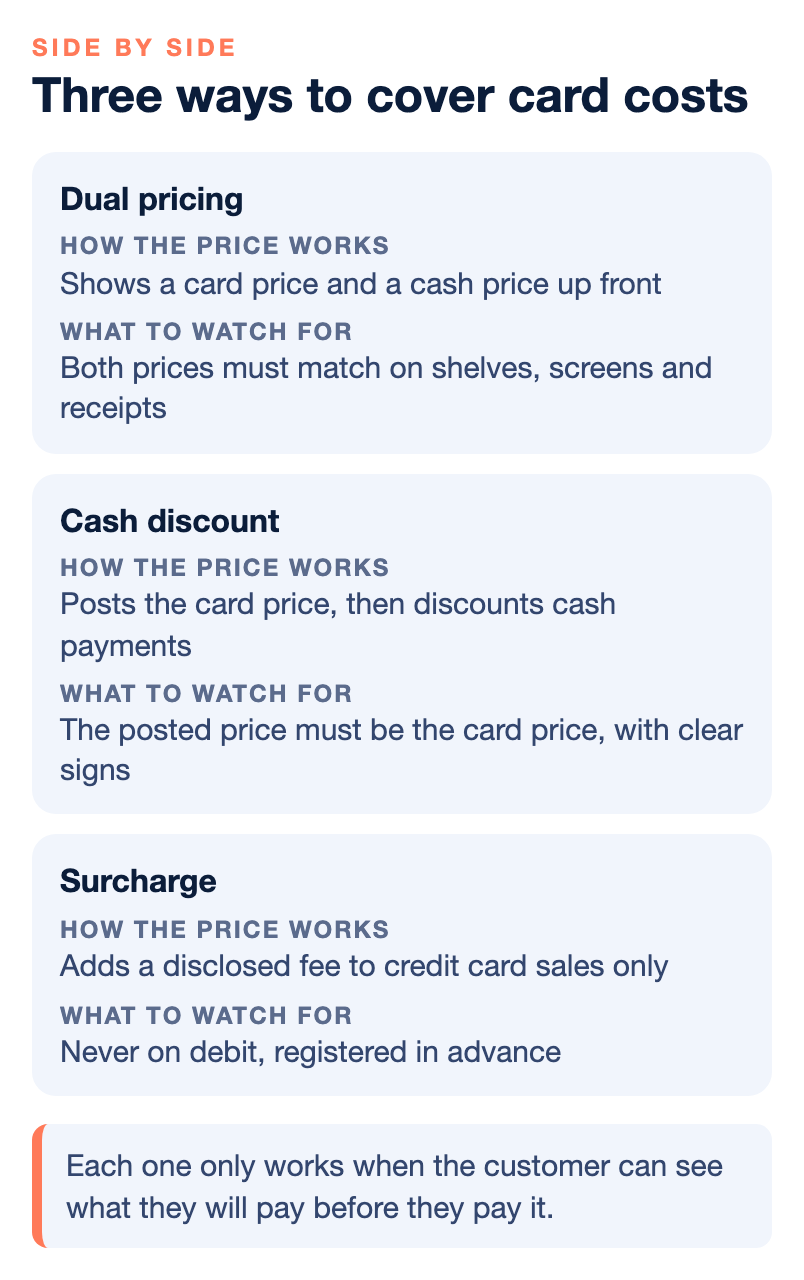
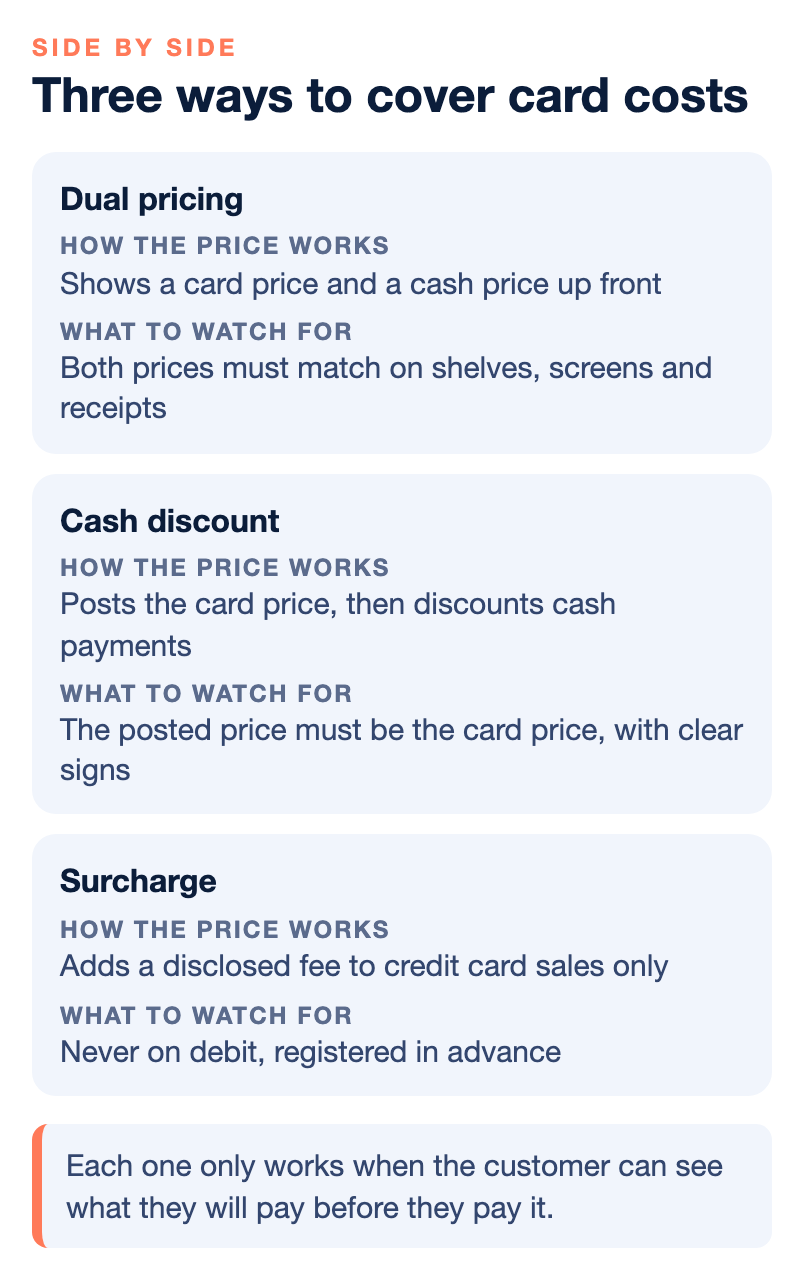
Dual pricing vs cash discount vs surcharge, side by side
Here is how the three compare on the points that usually decide the choice. Use it as a starting point, not a legal opinion, since the details of each program depend on how it is configured and where you operate.
| Model | How the price works | What to watch for |
|---|---|---|
| Dual pricing | Shows a card price and a cash price up front | Both prices must match on shelves, screens and receipts |
| Cash discount | Posts the card price, then discounts cash payments | The posted price must be the card price, with clear signs |
| Surcharge | Adds a disclosed fee to credit card sales only | Never on debit, registered in advance, capped by card network rules |
Notice what all three have in common. Each one only works when the customer can see what they will pay before they pay it. The models differ in where the price lives and how the difference is shown, and nearly every compliance problem we see comes from a mismatch between what the sign says, what the register charges and what the receipt prints.
How dual pricing works
With dual pricing, the higher card price and the lower cash price are both part of your pricing from the start. You decide the difference between them based on your real processing costs, your average ticket and your monthly volume, and your point of sale or terminal shows both prices to the customer and prints both on the receipt. When the customer pays by card, they pay the card price. When they pay with cash, they pay the cash price. Nothing is added at checkout, and nothing is taken away from a price the customer has not already seen.
Because the fee is built into the listed card price instead of being added after the fact, dual pricing avoids the surprise that makes customers resent a surcharge. That transparency is also why we recommend it for most in-person businesses. Your staff does not have to explain a line item at the register, your customer does not feel penalized for using a card, and the customer who prefers cash has a clear reason to keep using it.
Dual pricing also reaches beyond the counter. The same logic works on invoices, recurring billing and payment links, so a service company or a wholesaler can show a card price and a lower price for paying by bank transfer on every bill it sends. We cover that ACH angle in its own section below, because for many B2B companies it is where the biggest savings sit.
Two compliant ways to display dual prices
There are two accepted ways to present dual pricing, and every program we set up follows one of them.
- Post the card price only, and apply the cash discount at the register. Your menu, shelf tag or invoice shows one price, and that price is the card price. When a customer pays with cash, the system or the cashier applies the discount, and the receipt shows both the card price and the discount taken.
- Post both prices clearly. Your menu, shelf tag or invoice shows the card price and the cash price together, each labeled, with the card price listed first. Both prices then appear at the point of sale and on the receipt.
Either one is fine. What is never fine is posting only the lower cash price and then adding a fee at the register, because at that point you are surcharging, whatever your sign calls it.
What you should never do
- List only the cash price and add a fee later.
- Skip the disclosure at the entrance and at checkout.
- Use words like “convenience fee” or “card fee” without following the surcharge rules that those words trigger.
- Apply your pricing policy inconsistently, so one register, one server or one invoice template does it differently from the rest.
What can and cannot legally be passed to customers as a credit card surcharge?
A surcharge is the most regulated of the three models, so it is worth being precise about what it can and cannot be. Federal law allows businesses to surcharge credit cards, but some states restrict or regulate the practice, a few have banned it outright, and those laws have been changing. On top of state law, every major card network has its own surcharge rules, and you have to follow both.
In general terms, here is what a compliant surcharge looks like:
- Credit cards only. A surcharge can never be applied to a debit card, even when the customer runs the debit card as credit at checkout.
- Registered and noticed in advance. Most card networks require you to notify them and your processor before you begin surcharging, and to post customer notice ahead of time.
- Disclosed before the customer pays. The fee has to be clear at the register, on the payment page or on the invoice before the sale is completed.
- Its own line on the receipt. The surcharge must appear as a separate line item, not folded into the price.
- Capped. Most card networks cap a surcharge and do not allow you to charge more than what card acceptance actually costs you.
- Allowed where you operate. A few states restrict or ban surcharging, so check yours before you turn it on, and check again if you open a location somewhere new.
What cannot be passed along is just as important. A flat per-card fee posted at the register is one of the most common mistakes we see, because it is not structured the way the card networks require. A fee charged on debit cards breaks the rules no matter what the sign says. And a surcharge that is larger than your actual processing cost is a problem even when everything else is done correctly. If you have ever seen a “card minimum” or “card fee” sign and wondered whether it was allowed, our page on the Durbin Amendment, card minimums and flat fees walks through those rules in detail.
Card network rules and state laws change, and they are not the same everywhere. Confirm the current rules with your processor before you start, and for a legal question about your own business, ask an attorney.
The pros and cons of surcharging
Surcharging has real advantages. It passes the processing cost directly to the customer who chose the more expensive payment method, it lets you keep your base prices exactly where they are, and it is common and expected in professional services, B2B billing and government payments. For a business that sends large invoices, it can recover a meaningful amount without changing a single price.
The trade-offs are just as real. Some customers react badly to a fee added at the end of a sale, the rules are stricter than for the other two models, and surcharging is not available everywhere. In a face-to-face business, surcharges are harder for employees to explain and for customers to understand, which is why we usually steer in-person merchants toward dual pricing and keep surcharging for invoices and payment links, where the customer reads the bill before paying it.
Alternatives if you cannot or do not want to surcharge
If you operate somewhere that restricts surcharges, or you simply want to avoid the customer reaction, you still have options. A cash discount or dual pricing program offers a lower price for paying another way instead of adding a fee for credit. You can set your overall prices to account for processing instead of showing any visible difference. You can set a minimum purchase for credit cards within the limits federal rules allow. And for invoicing and B2B sales, you can encourage ACH bank payments, which cost far less to accept than cards and work well through payment links.
Why these programs are allowed at all
Cash discounting is not new. Gas stations, utilities, colleges and government offices offered lower prices for cash long before most small businesses could. What opened the door for independent merchants was the Durbin Amendment, part of the federal Dodd-Frank financial reform law passed in 2010, which gave merchants room to encourage lower-cost payment methods, offer discounts for cash and structure their pricing to reflect what card acceptance costs.
That flexibility came with rules, and the rules are where merchants trip. Federal law sets the outer frame, the card networks write their own requirements for how surcharges and discounts are shown, and individual states add display and disclosure rules of their own. A program that ignores any one of those three layers can create complaints, card network audits, forced changes to your program and, in the worst cases, the loss of your merchant account. Saving money only works if you keep it.
What a cash discount program actually does to interchange, and what it doesn’t
This is the part of the topic that confuses the most people, so it is worth saying plainly: a cash discount program does not make interchange go away. Interchange is set by the card networks and paid to the issuing bank on every card transaction, and no pricing program changes that. A rewards card still costs more to accept than a basic debit card, and every card sale still carries interchange, assessments and processor costs.
What a cash discount or dual pricing program changes is who pays for it. Under traditional pricing, you absorb the full cost of every card sale and keep less of each dollar. Under a cash discount or dual pricing program, the card price is set to cover that cost, so the customer who pays by card pays the price that includes it, and the customer who pays with cash pays less. The fees are still there. They are simply built into your pricing instead of coming out of your margin.
It helps to be just as clear about what a program does not do:
- It does not lower your interchange rates. If you want to reduce what you pay underneath the program, that is a separate conversation about your pricing model, and our guide to the four merchant account pricing models explains how each one shows those costs.
- It does not end chargebacks or fraud risk. Disputes still happen, and the protections you need to fight them still apply.
- It does not replace PCI compliance. You still need to complete your PCI requirements, and noncompliance can still carry its own fees.
- It does not make a debit surcharge legal. A program that adds a fee to debit cards is out of bounds whatever it is called.
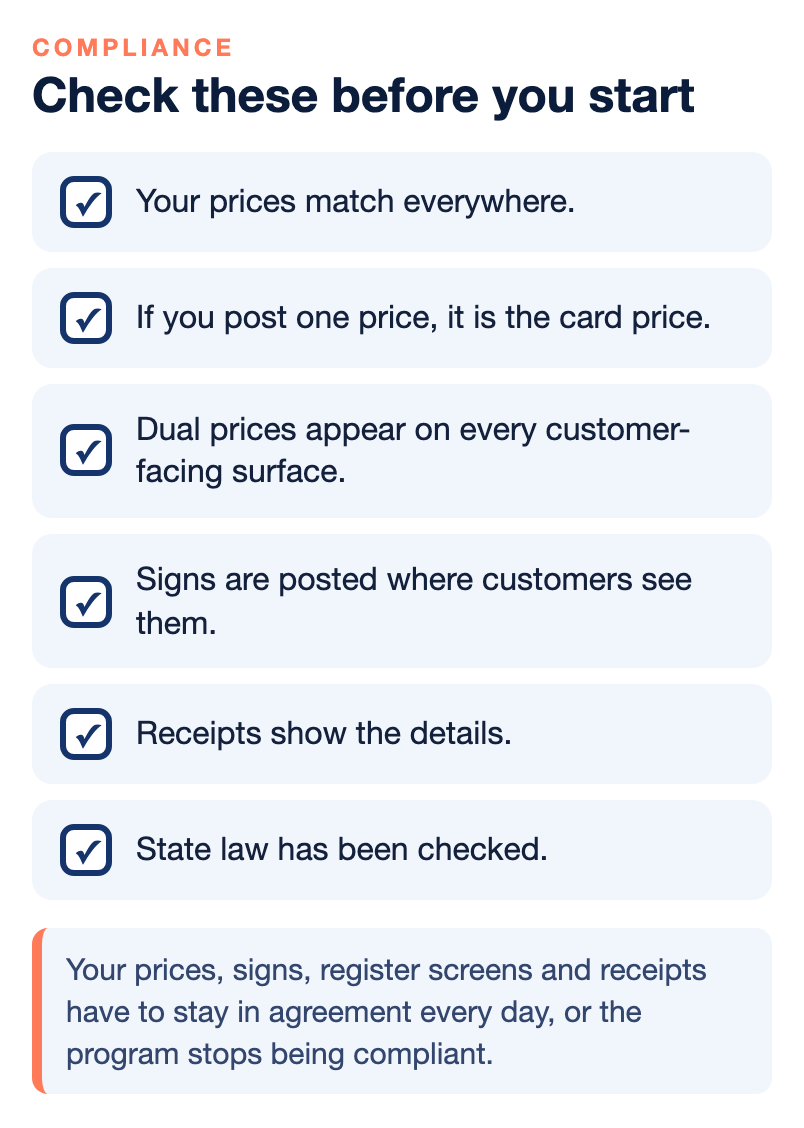
- It does not run itself. Your prices, signs, register screens and receipts have to stay in agreement every day, or the program stops being compliant.
What are the real costs of a cash discount program compared to just absorbing processing fees?
The honest comparison has two sides, and both have costs.
When you absorb processing fees, the cost is simple and constant. Every card sale arrives a little smaller than its price, the percentage grows as more customers pay with rewards cards, and over a year that adds up to a real line on your books. The advantage is that nothing changes for your customers or your staff. You keep one price for everyone, you never explain anything at the register, and you never have to think about signage.
When you run a cash discount or dual pricing program, most of that processing cost moves into your card price, so much more of each sale stays with you. But the program has costs of its own, and you should count them before you decide:
- Setup. Your terminal or point of sale has to be programmed to show and print the right prices. In many cases we can upgrade your existing terminal or POS, and sometimes new equipment is the better answer.
- Signage and menus. Shelf tags, menus, entrance signs and register signs all have to match the program.
- Staff training. Your team has to be able to answer the customer who asks why there are two prices.
- Customer reaction. Most customers accept transparent pricing, and some will notice. Clear signs and consistent prices are what keep that reaction small.
- Ongoing attention. Every price change has to reach the shelf, the screen and the receipt at the same time.
The way to compare the two for your own business is to start from your own statements. Look at what you paid to accept cards over the last few months, what share of your sales come in by card and how sensitive your customers are to price. That is the analysis we do before we recommend anything: we review your recent processing statements, your average ticket and your monthly volume, and we show you what traditional pricing costs you next to what a program would change. If the numbers do not justify the effort, we will say so. And if you start a program and decide it is not for you, we can reprogram your terminal and switch you back to traditional pricing.
The compliance checklist for cash discount and dual pricing
Whichever model you run, these are the points that keep it compliant. We check every one of them when we set up a program, and they are the same points we review when a merchant asks us to look at a program someone else installed.
- Your prices match everywhere. The prices stored in your point of sale must match your shelf labels, menus and signs. You can never show one price on the shelf and charge a different, higher price at checkout.
- If you post one price, it is the card price. When shelf labels or menus show a single price, that price must be the card price, and the cash discount is applied and itemized at the register.
- Dual prices appear on every customer-facing surface. If you show two prices, they must appear consistently on shelf tags, menus, register screens and receipts.
- Signs are posted where customers see them. Post clear signs at the entrance, at the register and on menus where they apply, saying that you offer a cash discount or use dual pricing and explaining the difference between the card price and the cash price.
- Receipts show the details. A compliant receipt shows the card price and the cash discount applied, or both prices under a dual pricing setup.
- State law has been checked. Card network rules come first, but some states have their own rules about how prices, discounts and fees are presented. Check yours, and check again when you add a location.
A simple sign covers most of the disclosure: “We offer a cash discount. All prices shown are for card payments. A discount is applied when you pay with cash.” The wording on your own signs should match how your program is actually set up.
The mistakes that get merchants fined
The same handful of errors show up again and again when we review programs that other providers installed. None of them are hard to avoid once you know to look for them.
- Calling a surcharge a cash discount. Many programs sold as “cash discount” are really surcharges with misleading signs, and the card networks treat them as surcharges.
- Shelf labels that do not match the register. Customers feel tricked when the price on the shelf is not the price they are charged, and they are right to.
- No signs before checkout. A missing disclosure is one of the fastest ways into a fine.
- Mixing debit and credit fees. Any fee on a debit card breaks the surcharge rules.
- Charging more than your actual processing cost. A surcharge has to reflect what card acceptance costs you.
- Receipt wording that does not match the program. The receipt is your record, and it has to say what actually happened.
- A point of sale that cannot do it properly. If your system does not support compliant dual pricing, you end up with mismatched records and compliance problems you did not create on purpose.
- Installing a program without reviewing state law. What is allowed in one state may not be allowed in the next.
How the card networks enforce the rules
Visa and Mastercard take pricing program rules seriously, and they do look. The card networks use secret shoppers and act on customer complaints, and a merchant caught surcharging without proper signs, or posting only the discounted cash price, can face fines, orders to refund customers and the shutdown of the merchant account. Even a single violation can lead to an audit. That is why we build compliance into the setup rather than leaving it to the merchant to remember.
State laws and why you must know your own
Most states allow these pricing models, but the rules vary, and they change. A few states restrict or ban surcharging. Some regulate how fees are disclosed, whether a fee must match your actual cost, how prices must be displayed and even which words you are allowed to use. Cash discount and dual pricing programs are broadly accepted when they are set up correctly, and some states still require you to post both prices rather than a single card price.
We are not the compliance police, and we will not hand you a list of states, because any list goes out of date. What we will do is make sure you know your own state’s framework before your program goes live. Ask your processor what applies where you operate, and for a legal question about your business, ask an attorney.
If you run a Florida business, the same advice applies. We are based in South Florida and have been since 2001, and we still confirm the current rules for every program we set up, because the right answer last year is not always the right answer today.
Seven myths about dual pricing
As dual pricing has spread from gas stations to retail, restaurants and B2B invoicing, so have the misunderstandings about it. These are the seven we hear most often.
Myth 1: Dual pricing is just surcharging. It is not. A surcharge adds a fee at checkout when a card is used, so the customer does not see the extra cost until the end. Dual pricing shows two clear prices up front, one for cash and one for card, so the customer sees the full picture before paying.
Myth 2: Dual pricing is capped like a surcharge. Card network caps are written for surcharges. A dual pricing program sets a card price and a cash price, and we set the difference around your real costs, your average ticket and your volume.
Myth 3: Dual pricing is complicated to implement. Not with the right system. Whether you use a terminal, a point of sale, invoicing or payment links, the setup can be simple, and your system does the math so your staff does not have to.
Myth 4: Dual pricing means passing fees on to customers. It is better described as choice and transparency. Your customers see both prices and pick the one that works for them, and when they understand they can save by paying with cash or bank transfer, many are happy to.
Myth 5: You cannot recover costs on debit transactions. That is true for surcharging, which can never apply to debit cards. Dual pricing works differently, because it lists two prices rather than adding a fee, and how card types are handled is part of your program setup, which we walk through with you.
Myth 6: Dual pricing is not compliant. It is compliant when it is structured properly, with signs, receipts and displays that meet card network and state requirements. Most problems come from programs that were set up carelessly, not from the model itself.
Myth 7: Dual pricing only works in person. It works in person, online and on invoices, including digital invoices, recurring billing and mobile checkout links. Contractors, professional firms and distributors use it as well as restaurants and stores.
The ACH angle: bank payments as the new cash
Many businesses think of this choice as credit versus cash, but for a company that sends invoices, the lower-cost option is usually an ACH bank payment. ACH costs far less to accept than a card, customers pay straight from their bank account with no paper check, and it fits naturally with monthly invoices and recurring billing.
This is where our own tools come in. Our NPSONE payment gateway handles cards, ACH and payment links in one place, and ClickBillR, the smart invoicing add-on for NPSONE, builds ACH directly into the invoices you send. Together they let you show dual pricing on card-present and card-not-present sales, offer a lower price for paying by ACH on every invoice, apply a compliant surcharge only where it is allowed, and sync payments back to your accounting software.
Here is how that looks for a service company that bills customers each month. Every invoice shows a card price and a lower ACH price, each with its own payment link, and the customer chooses. The customers who switch to ACH cost far less to collect from, the customers who prefer a card still have that choice, and nobody feels penalized at the end of the bill. For many B2B companies, that combination does more than surcharging alone, because it gives customers a convenient alternative to a card instead of just a fee for using one.
Which model fits which business
There is no universal answer, only the right answer for your business. What decides it is your average ticket, your customers, your industry, your local laws and how price sensitive your customers are. Here is where we usually land:
- Restaurants and retail stores: dual pricing, because showing both prices on menus, shelf tags and receipts builds trust and keeps the register simple.
- Convenience stores and fuel stations: dual pricing or a cash discount, which encourages more cash sales in a business where customers already expect two prices.
- Professional services and B2B companies: surcharging on credit card invoices, or dual pricing with an ACH option, because large invoices are where the fees hurt most.
- High risk merchants: any model that is set up correctly, because offsetting higher processing costs protects margins that are already under pressure.
You are also not required to choose just one. Some businesses run a cash discount in the store and a surcharge on invoices, some add ACH incentives on top of dual pricing, and some keep standard pricing and absorb the fees. There is no moral high ground here, just an informed decision. In our experience, dual pricing is the model that saves the most for most merchants while staying the easiest to keep compliant, and surcharging comes second because it can confuse both customers and employees.
How NPS sets up a compliant program
Our job is not to tell you which program to choose. It is to make sure you understand the difference, know your state’s framework, stay inside card network rules and have the program installed correctly. We have built compliance into our own platform so that your receipts and screens meet card network rules and your prices stay consistent at every point of sale.
We offer dual pricing and cash discount programs across:
- Credit card terminals: stand-alone hardware with automatic cash discounting.
- Retail point of sale systems: for convenience stores, liquor stores and other retailers.
- Restaurant point of sale systems: including server-based setups and pay at the table.
- The NPSONE gateway: dual pricing for ecommerce, invoicing and recurring billing.
- ClickBillR smart invoicing: cash and ACH discounts on invoices, with accounting sync, for B2B and service companies.
Every program comes with compliance support, staff training and point of sale setup, and we tell you up front which fee structure fits your business, including when the right answer is to keep absorbing the fees. If you want to see how one retailer paired a specialty point of sale with dual pricing, our retail POS and dual pricing case study shows how the pieces fit together.
When you are ready to sign up, the two program pages explain how we set each one up for you: our dual pricing program and our cash discount program. Our office is open from about 9 or 10 a.m. to 6 p.m., and merchants can reach 24/7 support through the help desk for their product. For more on fees, pricing and processing, browse our payments guides.
Where a pricing program is not the right choice
A pricing program is a money-saving tool when it is done right, and we would rather tell you it does not fit than install one that hurts you. Think twice if:
- Your customers are extremely price sensitive and a visible card price would send them to a competitor.
- Your point of sale cannot show matching prices on shelves, screens and receipts, and you are not ready to fix that first.
- You want one price for everyone and would rather absorb the cost than explain anything. Traditional pricing is always an option.
- You are thinking of surcharging in person at a busy counter, where a fee at the end of the sale is hard to explain. Dual pricing is usually the better fit there.
The bottom line
Dual pricing, cash discounting and surcharging are all legitimate, and all three can stop processing fees from eating your margin, but only when the price on the sign, the price at the register and the price on the receipt agree, and only when the program follows card network rules and your state’s law. For most stores and restaurants, dual pricing is the clearest and safest choice. For invoices and payment links, a registered surcharge or an ACH discount often fits better. And for the business whose customers would rather see one price, absorbing the fees is a reasonable decision, not a failure.
If you already run a program and are not sure it is compliant, or you want to see what each model would change on your own statements, talk with our team. We will review what you have, tell you what is right and what is at risk, and set it up properly.
Frequently asked questions
What is the difference between dual pricing, a cash discount and a surcharge?
Dual pricing shows a card price and a cash price side by side before the customer pays. A cash discount posts the card price and takes a discount off when the customer pays with cash or another lower-cost method. A surcharge adds a disclosed fee on top of the price, and only for credit card payments.
Is it legal to charge customers a credit card fee?
In most places, yes, if you follow the rules. A surcharge can only apply to credit cards, must be disclosed before the customer pays, must appear on the receipt and is capped by card network rules. A few states restrict or ban surcharging, so confirm the current rules with your processor, and ask an attorney about any legal question.
Can I add a surcharge to debit card transactions?
No. A surcharge can never be applied to a debit card, even when the customer runs the debit card as credit at checkout.
Can I just add a fee to card payments and call it a cash discount?
No. Adding a fee to card payments is a surcharge, whatever the sign says, and it has to follow surcharge rules. A real cash discount posts the card price and takes money off for paying with cash.
If I only show one price, which price has to be posted?
The card price. When your shelf tags or menus show a single price, it must be the card price, and the cash discount is applied and shown on the receipt at the register.
What signs do I need for a compliant program?
Post clear signs at the entrance, at the register and on menus where they apply, saying that you offer a cash discount or use dual pricing and explaining the difference between the card price and the cash price. Your receipts should show the same information.
Does a cash discount program get rid of interchange fees?
No. Interchange is still paid on every card sale. A cash discount or dual pricing program builds that cost into the card price, so customers who pay by card cover it and customers who pay with cash pay less.
Can I switch back to traditional pricing later?
Yes. If a program is not right for your business, we can reprogram your terminal and move you back to traditional pricing.