
The MATCH List: 14 Reasons Merchants End Up on It, and How Getting Off Really Works
CEO – Nationwide Payment Systems
The MATCH list is a database that acquiring banks and processors use to record merchants whose card processing was terminated for specific serious reasons, and a listing usually means you will need specialized underwriting before another bank will process for you. Mastercard sets the rules for it, there are 14 official reason codes, and a record typically stays in the system for several years. It is not a public list, not every closed account ends up on it, and getting a listing taken off is limited to a few narrow situations that run through the bank that entered it. We are Nationwide Payment Systems (NPS), a payment processor that has worked with high risk and niche merchants since 2001, and this guide explains what puts a business on MATCH, how to find out whether you are listed and why, what does and does not come off, and how to keep processing honestly while a listing is on file.
What is the MATCH list?
MATCH stands for Member Alert to Control High-Risk Merchants. You will also see it called the Terminated Merchant File, or TMF, which is the older name many people in the industry still use, and Mastercard now runs the system under the name MATCH Pro. Whatever the label, the idea is the same. When an acquiring bank, or a processor acting for one, closes a merchant account for certain serious reasons, it can enter that merchant into the database, and other acquiring banks check the database when a new application comes in. Visa and Mastercard both write the card rules that banks follow, and Mastercard is the network that sets the rules for MATCH itself: who reports, under which reason codes, how long a record stays and when it can be removed.
Two facts about MATCH surprise most of the merchants who call us. The first is that it is not a public database. You cannot search your business name online and see whether you are listed, the way you might look up a court record, because the system exists for acquiring banks and the processors who work for them. The second is that MATCH is about more than the company name. A record can include information about the business and its principal owners, the type of business, its websites, the date the account was terminated and the reason for the listing. That is why a listing can follow an owner into a new company, and it is why the honest approach always works better than a clever one.
It helps to see MATCH from the bank’s side. Every time an acquiring bank approves a merchant account, it takes on exposure for the transactions that run through it. If customers dispute charges, goods are never delivered or a merchant disappears after collecting money, the acquiring side can be left with the loss. MATCH is one of the ways banks warn each other about merchants that have already caused that kind of loss or broken the rules in a serious way. Seen that way, it is less a punishment than a shared memory, and the work after a listing is about showing a new bank that the memory no longer describes your business.
Is the MATCH list a blacklist?
Merchants call it a blacklist all the time, and we understand why, because a listing can shut a lot of doors at once. The word oversimplifies what the system does, though. MATCH is a risk-information system. It tells an acquiring bank that a merchant, or information connected to that merchant, was reported before and why. It does not order every bank to decline every application, and being listed does not automatically mean every acquiring bank will reject you.
What a listing does is change the conversation. A bank searching the database during underwriting will see the record, and from that point the questions get harder and the file gets heavier. Some reasons make new card processing extremely difficult to arrange. Others call for a clear explanation and the documents to back it up. The reason code matters enormously, which is why the most useful thing you can learn about your own listing is not that it exists but why it exists.
Does every terminated merchant account end up on MATCH?
No, and this may be the single most important point in this guide. Processors close accounts for many reasons, including a change to their own list of business types they will support, a mismatch between what was approved and what is being sold, or a risk decision that never rises to a MATCH reason. MATCH reporting applies only under specific circumstances that Mastercard’s rules define. So if a payment platform, an acquiring bank or another processor closes your account, do not assume you are on MATCH, and do not assume you are not. Find out.
We see this mix-up most often with instant-approval payment platforms, the kind that let a business sign up in minutes without real underwriting. Those platforms keep lists of restricted and prohibited business types, and they update those lists. A business can process for years, have its category added to the restricted list and get shut down one morning without having done anything new. That termination is painful, and it can come with held funds, but on its own it is not the same thing as a MATCH listing. The answer only comes from asking the right people the right questions, which we cover below.
What puts a merchant on MATCH: the 14 reason codes
Every MATCH record carries a reason code that says why the merchant was reported. Mastercard publishes the codes, and there are 14 of them. Here they are in plain words, the way we explain them to business owners. Read them as categories rather than accusations, because a code describes what the reporting bank says happened, and the details behind any one listing can be very different from the label.
| Code | Reason | What it means in plain words |
|---|---|---|
| 01 | Account data compromise | The business had a data breach that exposed cardholder data. |
| 02 | Common point of purchase | The business was the common link in a number of fraud cases. |
| 03 | Laundering | The account processed payments for another business that was never disclosed. |
| 04 | Excessive chargebacks | Chargebacks went over the allowed thresholds. |
| 05 | Excessive fraud | Fraud levels went over card network standards. |
| 06 | Fraud conviction | A business owner was convicted of fraud. |
| 07 | Fraudulent identity | False or stolen information was used on the application. |
| 08 | PCI noncompliance | The business failed to meet the card security standards. This one is rare. |
| 09 | Bankruptcy or liquidation | A bankruptcy was tied to fraud or risk concerns. |
| 10 | Violation of standards | The business broke Visa or Mastercard rules not covered by another code. |
| 11 | Merchant collusion | The business worked with others to commit fraud. |
| 12 | Illegal transactions | The account processed illegal or prohibited sales. |
| 13 | Identity theft | The merchant account was opened using a stolen identity. |
| 14 | Miscellaneous | Any other reason Mastercard accepts as justified. |
The codes fall into a few natural groups, and the group tells you a lot about what a new bank will want to see.
Security and data codes
Account data compromise, common point of purchase and PCI noncompliance are about how card data was protected. A business can land here without anyone at the company meaning harm, for example after a breach of an outdated system. What a new bank wants to see is that the hole has been closed: current PCI compliance, updated equipment and software, and a clear account of what happened and what changed.
Fraud and identity codes
Excessive fraud, fraud conviction, fraudulent identity, merchant collusion and identity theft are the codes that make new processing hardest to arrange, because they go to the heart of whether a bank can trust the people behind the account. Identity theft is the exception that deserves special attention. Sometimes a person discovers a listing for an account they never opened, because someone used their personal or business information to set it up, run transactions and walk away. If that may be your situation, read our guide on being on the MATCH list when you did nothing wrong, which walks through how to investigate it.
How the account was used
Laundering, illegal transactions and violation of standards are about using the account for something it was not approved for. The most common version we see is transaction laundering, which we explain in its own section below. These codes often come from a business that grew or changed without telling its processor, which is why prevention here is mostly about disclosure.
Money and risk codes
Excessive chargebacks and bankruptcy or liquidation are about losses. Chargebacks are the most frequent reason businesses get flagged, and they are also the reason most within a merchant’s control, since better descriptors, faster customer service and clear refund policies all bring them down. The last code, miscellaneous, covers any other reason Mastercard accepts, so if your listing carries it, the explanation from the reporting bank matters even more than usual.
The everyday mistakes behind many listings
The reason codes are the official vocabulary, but most of the MATCH files we review started with ordinary business decisions that nobody thought twice about. None of these are exotic, and every one of them is avoidable once you know the rule behind it.
- Not following the processor’s terms of service. Your merchant agreement and the processor’s terms set out what you may sell and how. Breaking them, even by accident, can end an account. Read the terms, and read them again when the processor sends an update.
- Letting chargebacks drift up. A high chargeback ratio is one of the most frequent triggers. Keep chargebacks as low as you can, and ask your processor where its warning line sits, because the limit any bank accepts depends on the business type and model.
- Selling products that were never approved. If you add products or services that were not part of your original application, your processor may treat that as a breach. Get new products approved before you sell them.
- Running several websites on one account. Every website connected to your merchant account has to be on file. You cannot get an account for one site and plug the same gateway into several others.
- Missing website policies. A site that takes cards should show a privacy policy, terms and conditions, return, refund and cancellation policies, and the business name, address, phone number, email address and a contact form. If you bill on a recurring basis, canceling should be as easy as signing up, and regulators are enforcing that.
- Advertising that breaks the rules. Deceptive or noncompliant ads can lead to a termination, and in serious cases to a listing.
- Skipping a required registration. Some business types must be registered with the card brands before they process, including prescription drugs and telemedicine, adult websites with recorded or live content, direct marketing, cigars and vape sold online, and games of chance. If you are in one of these, make sure you are registered.
- Leaving debts unresolved. Unpaid fees, unsettled balances and unaddressed chargebacks with a processor can turn a closed account into a much bigger problem.
If any of these describe your business today, the good news is that each one can be fixed before it turns into a termination. Our guide to the restricted merchant label explains how banks sort business types into categories, which is often where these problems begin.
What is transaction laundering?
Transaction laundering means using a merchant account to process payments for activity that was never approved on that account. The simple version looks like this. Company A is approved for processing. Company B cannot get processing. Company A starts running Company B’s transactions through its own account, perhaps as a favor to a friend or for a small cut. That is not a workaround. It is one of the clearest paths onto MATCH, and it can put both companies and their owners in a very difficult position. A merchant account should be used only for the business and the activity it was approved for, and never to process payments for anyone else.
How do I find out if I am on the MATCH list?
Because MATCH is a system for acquiring banks rather than a public lookup, you find out through the banks and processors, not through a search engine. Most merchants discover a listing in one of three ways.
- Ask the processor that closed your account. Most businesses learn about a listing around the time their account is terminated. Ask that processor directly whether you were reported.
- Request a MATCH inquiry. Processors and acquiring banks have access to the system, so a processor can run an inquiry that confirms whether you are listed. If you are not sure where to start, contact us and we will tell you how to go about it.
- Watch for a pattern of denials. If you keep getting declined for new merchant accounts and nobody will say why, a listing may be the reason, and it is worth asking the question directly.
When you reach the bank or processor responsible for the account that was closed, ask whether the business or any principal connected to the account was submitted to MATCH. If the answer is yes, ask for four things in writing: the reason code, the date of the listing, the name of the acquiring bank responsible for it, and any information they can share about the basis for it. Write down who you spoke with and when, and follow up by email so there is a record. A new acquiring bank may also find the listing during underwriting, which is exactly why it is far better to learn the details yourself first.
Why the reason code matters so much
Knowing “I am on MATCH” is not enough to plan anything. The reason behind the listing can change whether another acquiring bank is willing, or even permitted, to approve your business. A breach that has been fixed and documented reads very differently to an underwriter than a fraud conviction, and a chargeback problem that was solved reads differently from one that is still going on. Until you know the code, you do not know which problem you are solving, and you cannot tell a new bank a complete and accurate story.
How long does a MATCH listing last?
A MATCH record typically stays in the system for several years, after which Mastercard’s rules have it purged automatically. That length is a big part of why a listing has such an impact, and it is also why waiting it out is rarely a plan on its own. This is not something to ignore and hope it disappears in a few months. Check the current period with the acquiring bank that listed you, and treat the time in between as the window to fix what caused it and to build the record that shows it was fixed.
One thing a listing does not touch is your credit score. MATCH is separate from the credit bureaus and does not affect personal or business credit. It affects your ability to get card processing, which for many businesses is serious enough.
What does not come off: how removal really works
This is where most of the bad information about MATCH lives, so we want to be plain about it. Removal is not available simply because a merchant disagrees with a listing, and calling Mastercard to explain your side is generally not how the system works. Mastercard’s rules allow removal in limited situations. The main one is when the bank or processor that entered the listing reports that the merchant was added in error. The rules also include a specific path for certain PCI noncompliance listings once the merchant has become compliant and that has been confirmed.
Who can take a listing off? In practice, the acquiring bank that entered it, working through Mastercard’s process. Not the merchant, not a consultant and not a new processor. We cannot remove anyone from MATCH, and nobody outside the bank that made the listing can honestly promise to. If someone offers to make a listing disappear for a fee, treat that as a warning sign.
So the first question in any removal effort is not “How do I get Mastercard to delete me?” It is “Was I listed correctly in the first place, and which reason code applies?” If the listing was a mistake, there is a real process to correct it. If it was accurate, the path forward is fixing the cause, documenting the fix and finding an acquiring relationship willing to look at the whole picture.
If you believe the listing is a mistake
Mistakes happen. Information can be entered against the wrong business, a listing can be filed under the wrong reason, or the account in question may not have been yours at all. If you believe the listing is wrong, the bank responsible for entering it is the place to start, and documentation is what gives your request weight.
- Identify the acquiring bank responsible for the listing.
- Get the reason code and the explanation behind it.
- Gather your documents: termination notices, processing statements, correspondence, PCI compliance records, chargeback records, proof of business ownership and proof about the activity the listing describes.
- Put your dispute in writing and ask the bank to review the listing.
- Keep copies of everything, and do not rely on phone calls alone.
If you believe you were added unfairly and the bank will not engage, it may be time to speak with an attorney who handles merchant processing disputes. Our B2B Vault episode on the MATCH list is a conversation with an attorney about exactly these situations, and it is worth a listen before you decide on your next step.
If the problem was PCI compliance
Card security listings are the clearest case where fixing the problem can lead to removal, because Mastercard’s rules include a specific process for certain PCI noncompliance listings after compliance is confirmed. Even so, becoming compliant does not take the record off by itself. Work through the acquiring bank that listed you, follow its process and keep proof of every step.
What to do in the first days after you find a listing
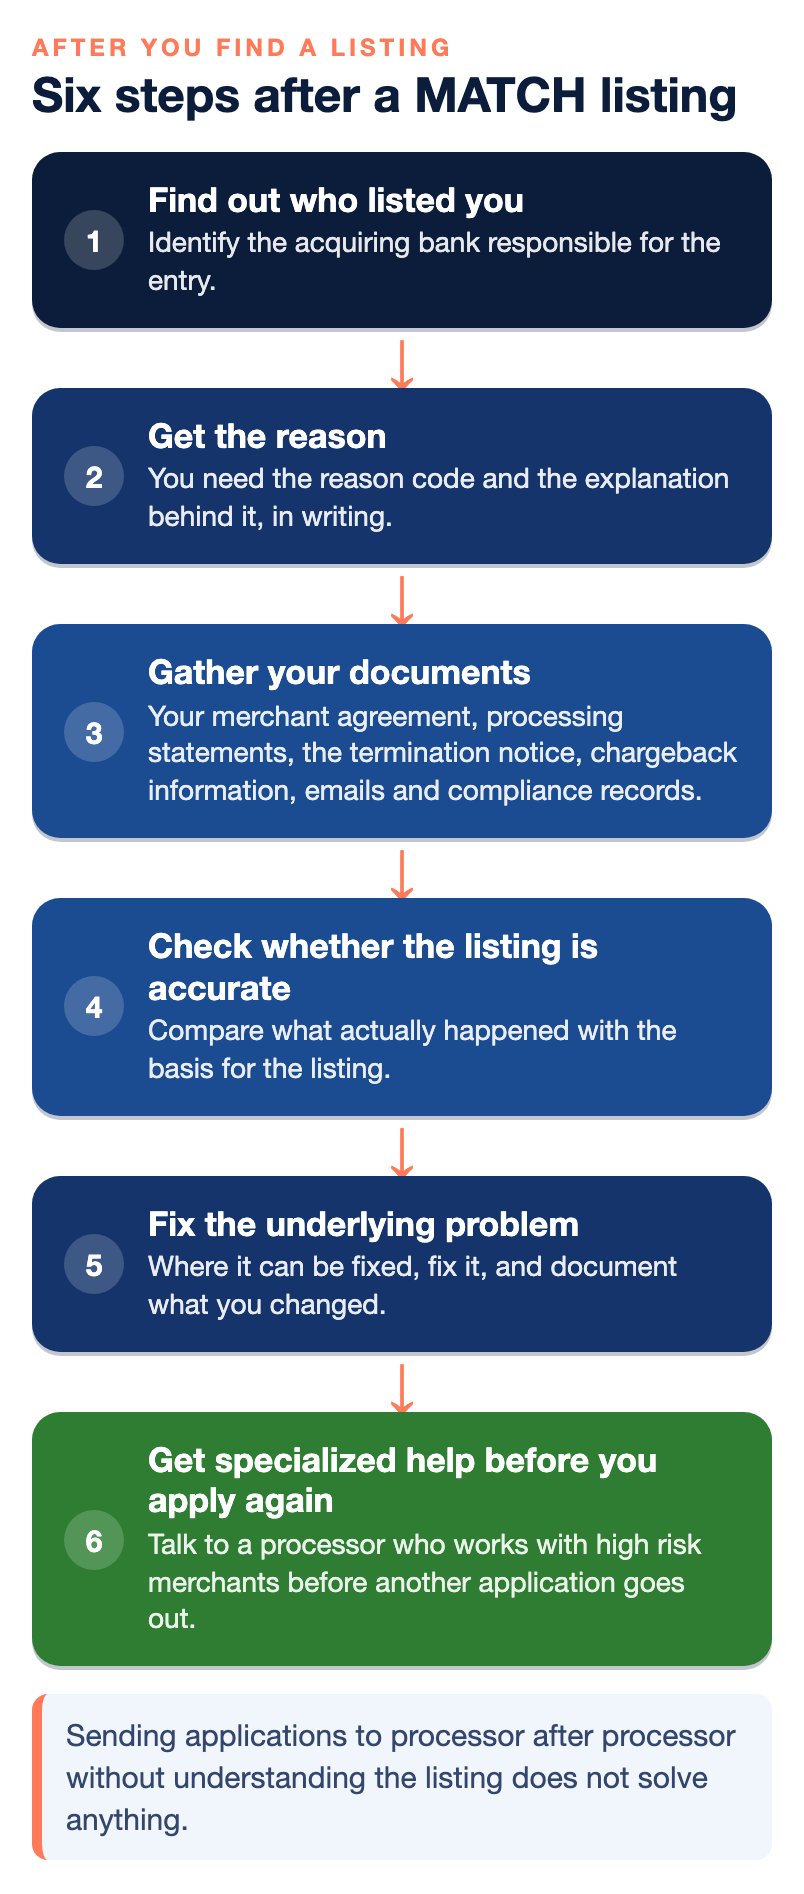
The first reaction to a MATCH listing is usually to apply everywhere at once, and that is the one move we would talk anyone out of. Sending applications to processor after processor without understanding the listing does not solve anything, and each one can add another decline to your history. The better order looks like this.
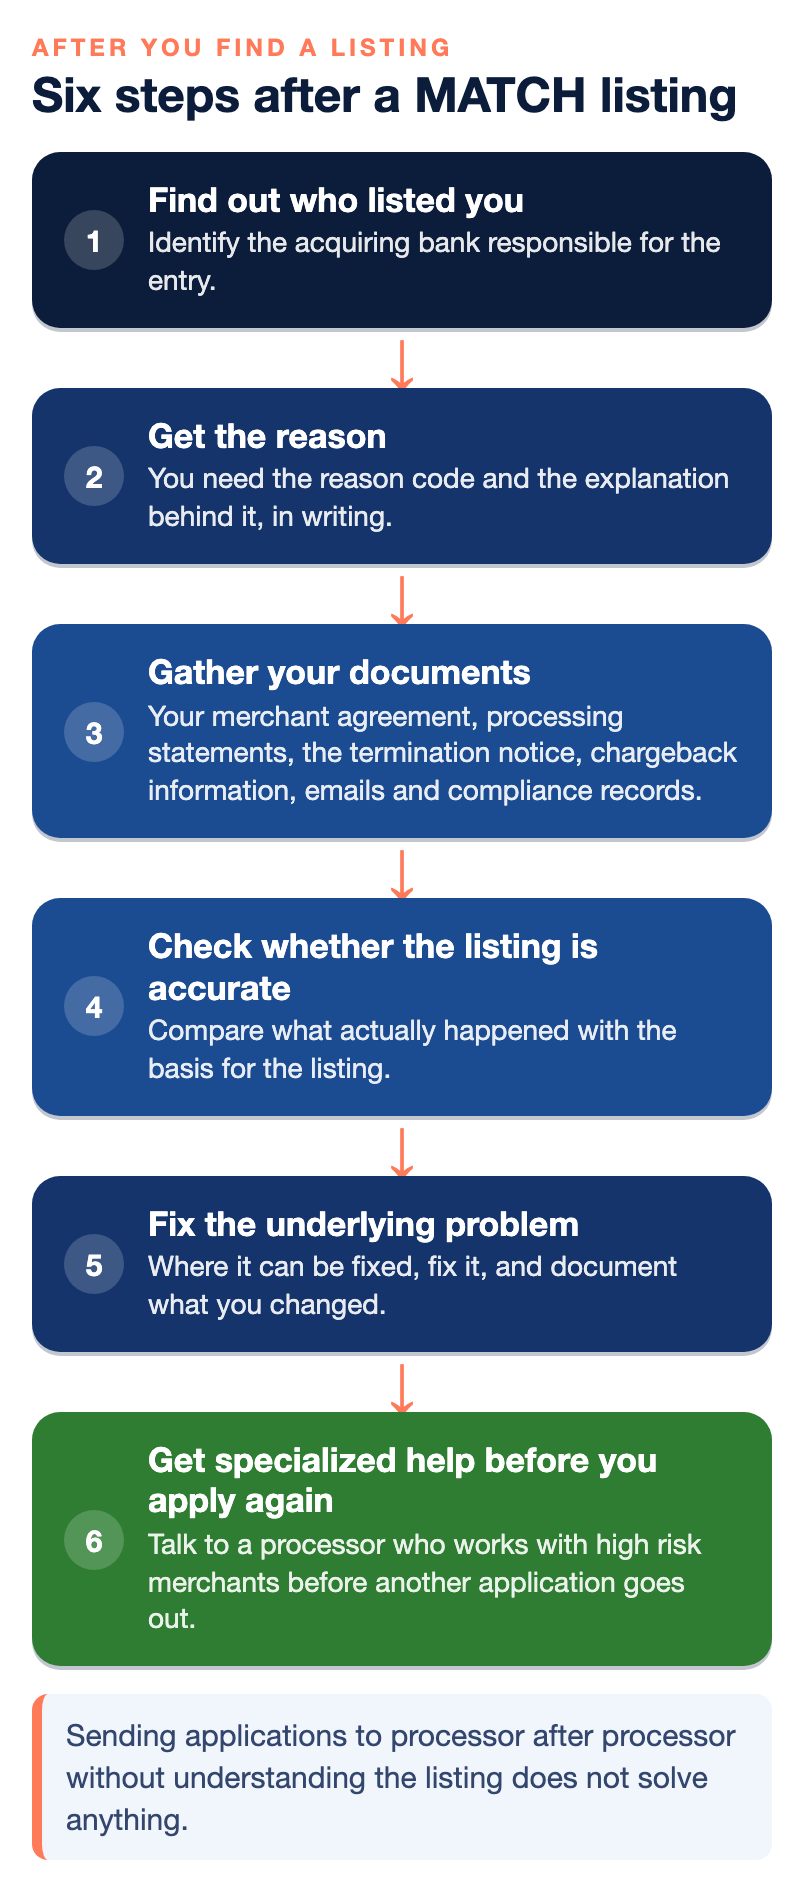
- Find out who listed you. Identify the acquiring bank responsible for the entry.
- Get the reason. You need the reason code and the explanation behind it, in writing.
- Gather your documents. Your merchant agreement, processing statements, the termination notice, chargeback information, emails and compliance records.
- Check whether the listing is accurate. Compare what actually happened with the basis for the listing.
- Fix the underlying problem. Where it can be fixed, fix it, and document what you changed.
- Get specialized help before you apply again. Talk to a processor who works with high risk merchants before another application goes out.
High risk underwriting is about presenting a complete and accurate story. These six steps are how you build one, and they are the same steps whether the listing turns out to be a mistake or a fair record of something that went wrong.
What acquiring banks actually do with a listing
When an acquiring bank finds a MATCH record during underwriting, it does not stop reading. It weighs the listing against everything else it knows about the application, and there is no single answer to whether it will approve. The outcome depends on the reason for the listing, the industry, the time since the termination, the business’s financial condition, its processing history, who owns it, how it operates, the bank’s own policy and, above all, whether the underlying issue has been corrected.
Some MATCH situations make new approval extremely difficult. Others mainly require more explanation and more paper. A bank that works with high risk merchants may review a listed merchant case by case, and the merchants who do best are the ones who arrive with the reason code, the documents and a clear account of what changed. The merchants who struggle are the ones who hope the bank will not notice.
Can a new company name get around MATCH?
No, and trying is a mistake. Underwriting looks well beyond the business name. Banks examine ownership, principals, business addresses, websites, tax information, processing history and related companies, and a MATCH record can carry information about the owners as well as the business. Starting a new corporation to hide a listing or a previous processing history is not a legitimate strategy, and it tends to turn a solvable problem into a much worse one. The right approach is disclosure and specialized underwriting, not disguise.
Can you still accept cards while you are listed?
Possibly, depending on the reason code and the underwriting of the bank reviewing you. Many listed merchants who do find processing find it through providers that specialize in high risk accounts, and that usually means stricter terms, closer monitoring, less flexibility and higher costs than a standard account. That trade can still be worth making, because it keeps the business running while the listing ages out and the record of clean processing grows. Just go in with your eyes open, and read the terms before you sign.
How to stay off the MATCH list
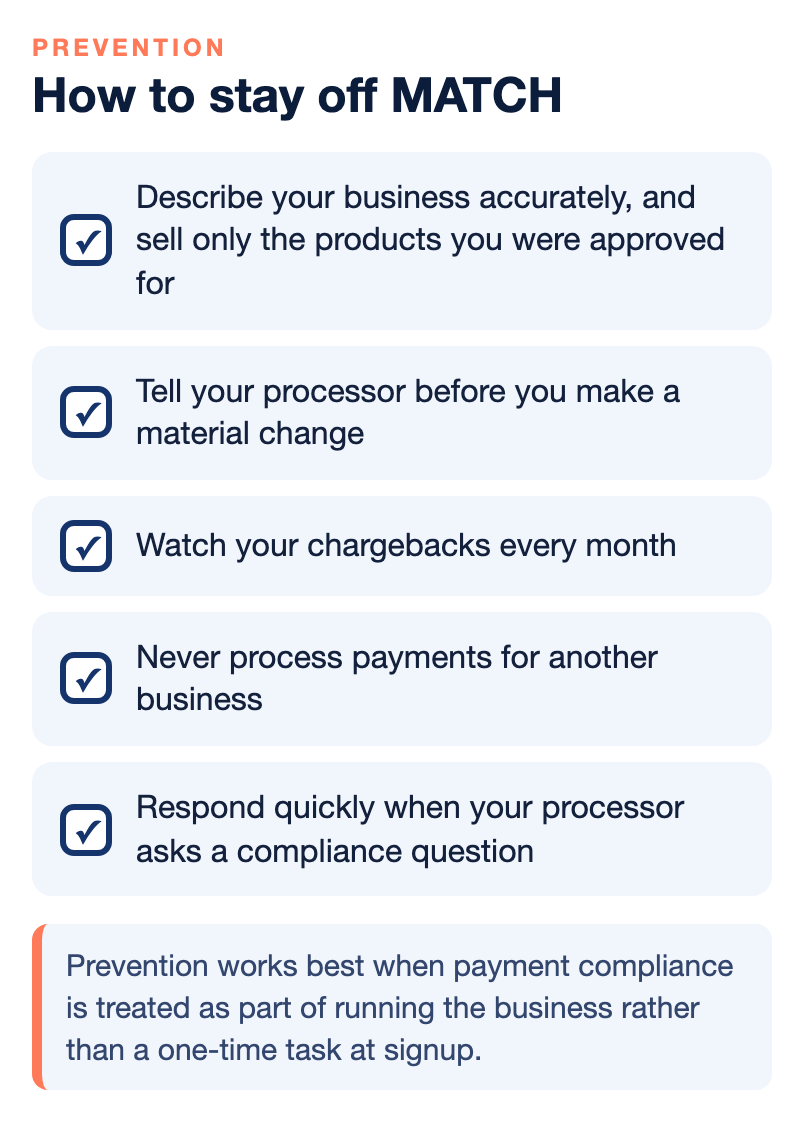
The best MATCH strategy is never needing one. Prevention is not complicated, but it is ongoing, and it works best when payment compliance is treated as part of running the business rather than a one-time task at signup.
- Describe your business accurately on the application, and sell only the products you were approved for.
- Tell your processor before you make a material change, such as new products, a new website or a new way of billing.
- Watch your chargebacks every month, answer customers within a day, keep a phone number that someone actually answers, and make your refund policy easy to find.
- Stay PCI compliant and keep your equipment and software current.
- Follow the card brand rules for your industry, including any registration they require.
- Keep your licenses current and your website compliant.
- Never process payments for another business.
- Respond quickly when your processor asks a compliance question.
There is a bigger point underneath that list. Mainstream payment platforms work well for millions of ordinary businesses, but specialized industries often need more careful underwriting. If you sell CBD, tobacco or vape products, supplements, telemedicine services, firearms, adult products or other higher risk goods and services, you need a processor that understands what you sell. Squeezing a high risk business into a platform that does not want it is one of the most common ways merchants end up terminated, and sometimes listed. Our high risk merchant services page explains how a properly underwritten account works.
How Nationwide Payment Systems can help
We work with merchants in specialized and high risk industries every day, and one of the things we focus on is keeping merchants off MATCH in the first place by reviewing their websites and business practices so they stay within the rules. If you have been terminated, or you think MATCH may be involved, we can look at the situation with you before another application goes out. That review usually covers your processing history, the termination, any MATCH information you have, chargebacks, products, your website, licenses, compliance documents and what underwriting is likely to ask for.
We want to be clear about what that review is and is not. It is an honest read of where you stand and what your options might be. It is not a promise of approval, and it is not a way to get a listing removed, because only the bank that entered a listing can do that. Not every MATCH situation can be solved. But knowing exactly what you are dealing with is the first step, and it is the step most merchants skip.
Our office is open roughly 9 or 10 a.m. to 6 p.m., and merchants who already process with us reach 24/7 support through the help desk for their product. To talk through a termination or a listing, contact us. For more on how processing works, from pricing to chargebacks, browse our payments guides.
The bottom line
A MATCH listing is serious, and it deserves a plan rather than panic. Find out whether you are actually listed before you assume anything, get the reason code and the name of the bank that listed you in writing, and fix whatever caused it. If the listing is wrong, dispute it with that bank and back it up with documents. If it is right, stop applying everywhere, assemble a complete and honest file and work with a processor who understands high risk underwriting. Nobody can promise to take you off MATCH, and you should be wary of anyone who does. What you can control is whether the next bank that reads your file sees a business that hid its history or one that understood it and fixed it.
Frequently Asked Questions
What is the MATCH list?
The MATCH list, short for Member Alert to Control High-Risk Merchants and also called the Terminated Merchant File, is a database acquiring banks and processors use to record merchants whose accounts were terminated for specific serious reasons. Mastercard sets its rules and now runs it as MATCH Pro. It is not a public database.
How do I know if my business is on the MATCH list?
Ask the processor or acquiring bank that closed your account whether the business or any principal was submitted to MATCH, and ask for the reason code, the date and the bank responsible in writing. A processor can also run a MATCH inquiry. Many merchants first suspect a listing after a pattern of denials.
Does every terminated merchant account go on MATCH?
No. Processors close accounts for many reasons, and MATCH reporting applies only under specific circumstances set by Mastercard’s rules. A closed account is a reason to ask the question, not proof that you are listed.
How long does a merchant stay on the MATCH list?
A MATCH record typically stays in the system for several years and is then purged automatically under Mastercard’s rules. Confirm the current period with the acquiring bank that listed you, and use that time to fix the cause and document the fix.
How do I get off the MATCH list?
Removal is limited. The main path is the acquiring bank that entered the listing reporting that it was added in error, and Mastercard’s rules also include a process for certain PCI noncompliance listings once compliance is confirmed. Only the bank that made the listing can request removal, so nobody else, including NPS, can promise it.
Can I get a merchant account if I am on MATCH?
Possibly. It depends on the reason code, your industry, the time since the termination, your processing history, ownership and whether the problem was fixed, along with the bank’s own policy. Arrive with the reason code, your documents and a clear account of what changed, and expect stricter terms if you are approved.
Will being on the MATCH list affect my credit score?
No. MATCH is separate from the credit bureaus and does not affect personal or business credit. It affects your ability to get card processing.
Can I start a new company to get around MATCH?
No. Underwriting looks at owners, principals, addresses, websites, tax information, processing history and related companies, and a MATCH record can include information about the owners. Hiding a listing behind a new company tends to make the problem worse. Disclosure and specialized underwriting are the right approach.